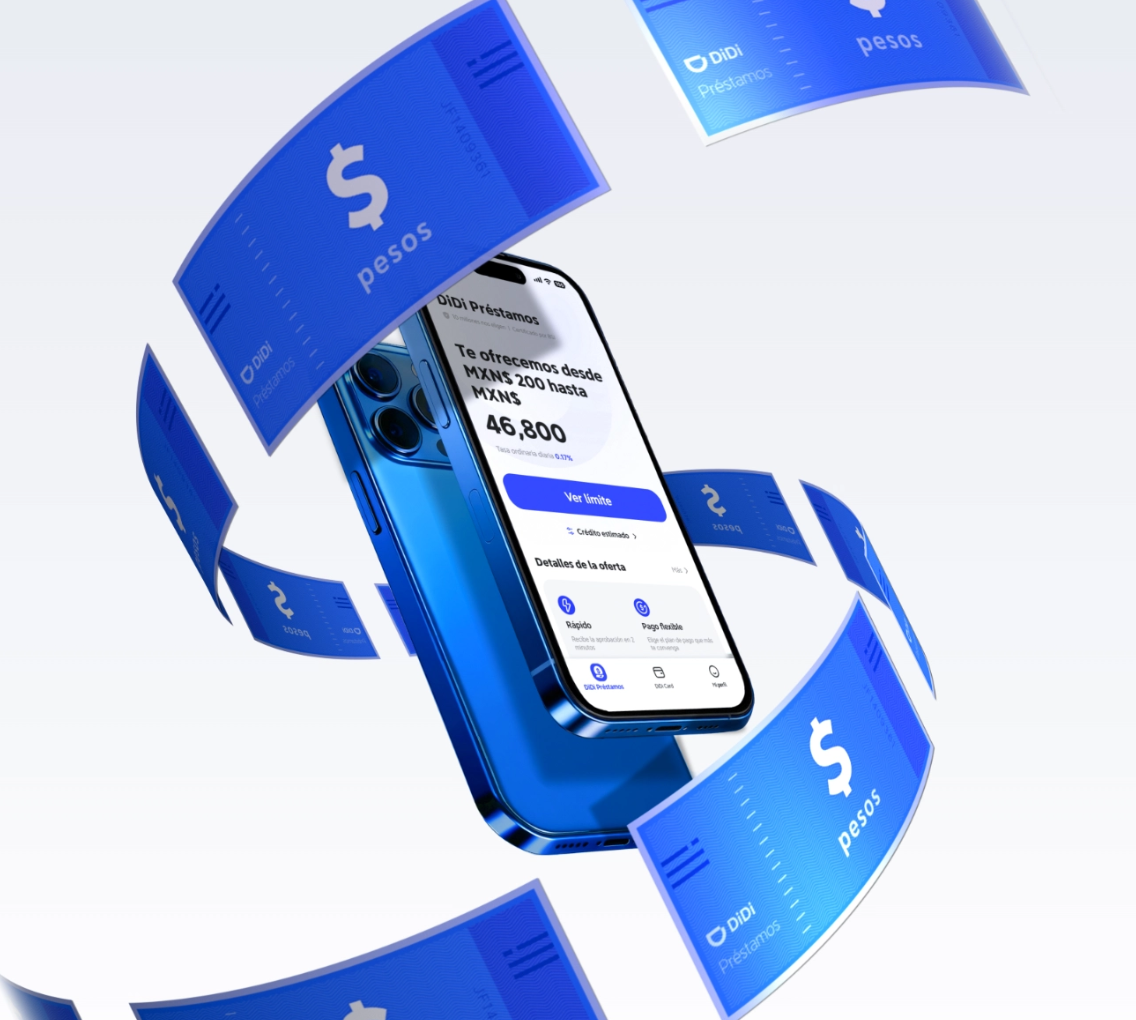
User-first reality check
Listen — if you’re tryna stretch payments without the headache, you want options that actually move fast and don’t ask you to mortgage your cousin. The practical move is a simple digital card that gives clear installment plans; enter the didi card, built around user needs like quick onboarding, transparent APR language, and an accessible credit line. This ain’t marketing fluff: it’s about replacing paperwork with app flows so people can buy what they need and pay over time without surprises.
What matters to users, straight up
Folks care about three things: predictable monthly payments, minimal friction to sign up, and the ability to use the card across merchants. A great product nails those while keeping fees visible. Real-world anchor — go look at CDMX transit hubs and corner tiendas: post-2020, merchants leaned hard into digital payments. That shift created demand for consumer-friendly installment options that don’t need a guarantor, and that’s the gap DiDi Finanzas is stepping into with its tarjeta de credito en linea approach.
How DiDi Finanzas approaches no-aval installments
They focus on a few concrete levers: frictionless verification, merchant partnerships for point-of-sale installments, and clear repayment schedules. Translation: you get a defined installment plan (months without interest on select purchases), a digital approval path, and merchant financing that integrates at checkout. The UX matters — a clean credit decision flow makes a difference for adoption and lowers default risk.
Common mistakes users make — and how to avoid them
People jump for the shiny “0% for X months” and ignore the fine print. That’s a trap. Avoid these moves:
– Accept offers without checking whether interest-free applies only to specific merchants or product categories.
– Overextend based on a headline credit limit; the usable line and minimum payments can still strain monthly cash flow.
– Forget to confirm how returns or cancellations affect installment plans — accounting mismatches happen at merchant-processor handoffs.
Be smart: prioritize clear disclosure of APR-equivalent costs and set an affordable monthly budget before you swipe.
Alternatives and comparative insight
There are other players doing installment credit, from bank-backed cards to fintech buy-now-pay-later rails. Compared to those, a product tied into a large mobility and services brand can offer broader merchant reach and tailored promos. But banks might offer deeper credit lines and longer credit history impact. Pick based on how you plan to use the card: everyday purchases vs. occasional big-ticket buys — that decides whether you want merchant-driven promos or classic revolving credit.
Tech and trust — what you should vet
Check for strong encryption on the app, a clear privacy policy, and real-time transaction alerts. Also inspect underwriting signals: are they using alternative data sources to avoid excluding people without long credit histories? That reduces reliance on cosigners while still managing risk. — Notice if the app shows projected payment schedules before you accept the plan; that’s a good sign.
Summary of practical takeaways
Users win when providers deliver transparent installment mechanics, real-time approvals, and merchant coverage without demanding a guarantor. DiDi Finanzas positions itself in that sweet spot by focusing on usability, merchant integration, and digital-first onboarding — all centered around making no-aval, interest-free months actually usable for regular people.
Three golden rules for choosing the right tool
1) Verify effective cost: don’t just read “0%” — confirm which purchases qualify and whether fees or late penalties change the math. 2) Confirm merchant reach: if you can’t use the card where you shop most, the perks vanish fast. 3) Test the repayment visibility: choose providers that show exact installment schedules and send alerts before due dates.
For practical, everyday value — from simple sign-up to usable installment plans — DiDi Finanzas fits where user needs and merchant access meet. –